Panel Data Econometrics
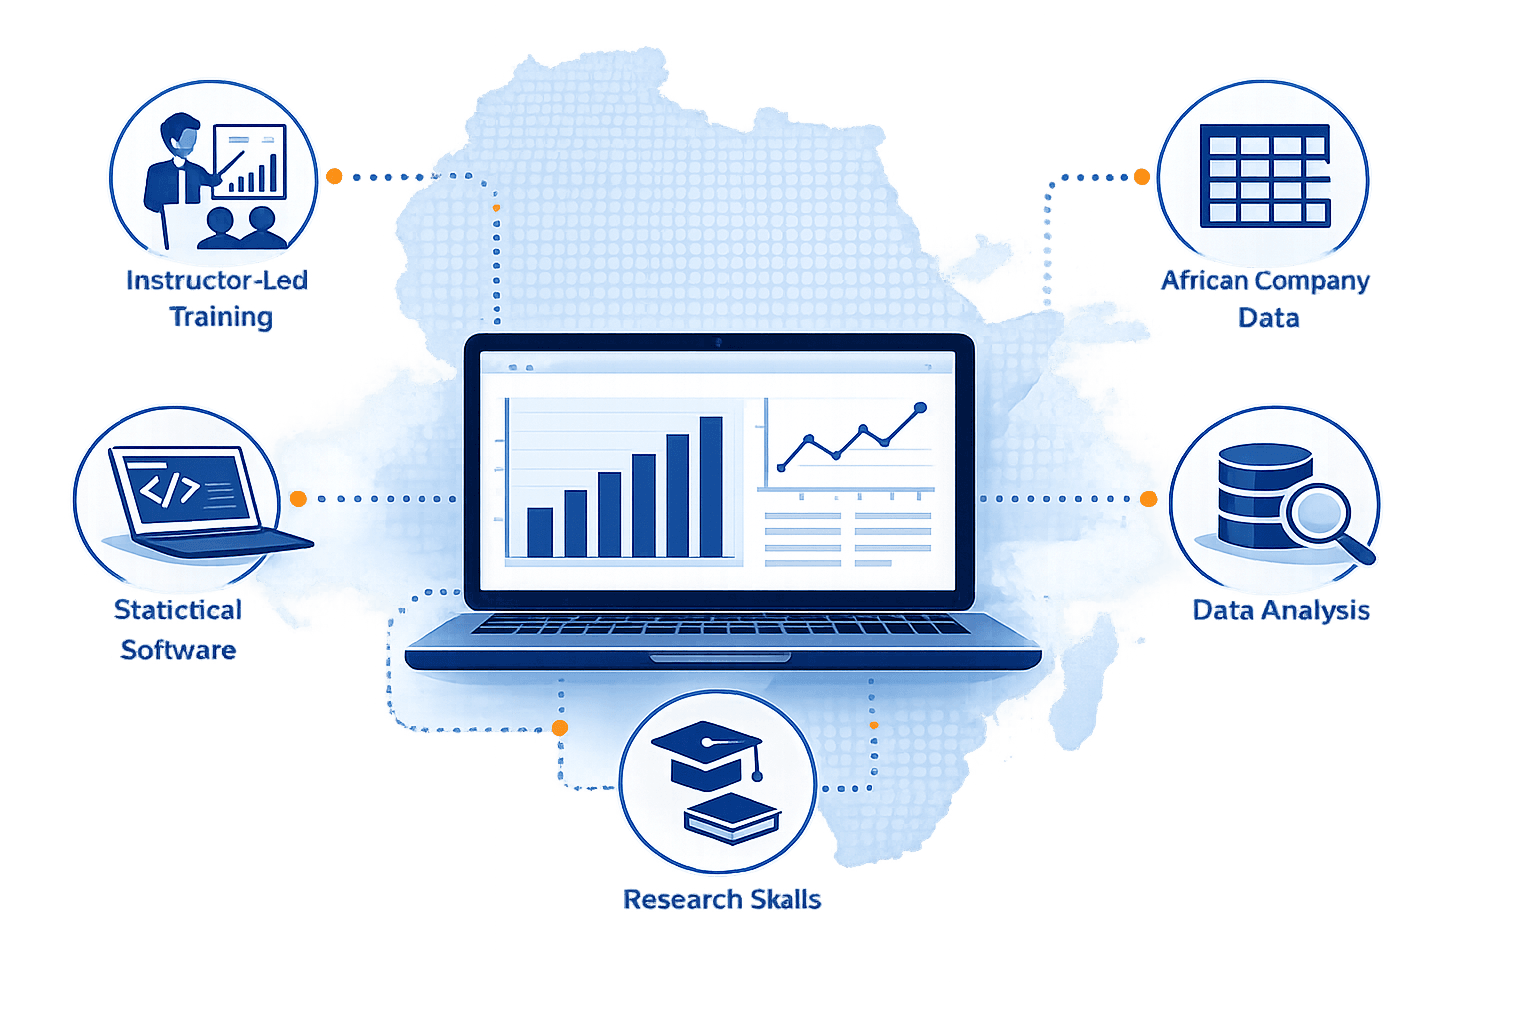
A comprehensive programme covering the theory and application of panel data models in accounting and finance research. Topics include fixed and random effects, dynamic panel models, instrumental variables, and robustness testing.
Online LiveIn-PersonPre-Recorded
- Duration
- 30 minutes per recorded module.
- Audience
- Postgraduate students, Academic faculty, Corporate finance teams
- Certificate
- Yes